A Property Is Sold. So Why Might the Revenue Still Be Unrecognised?
A real estate developer signs a sale agreement for an apartment, receives payments from the buyer and reports strong bookings for the quarter. Yet, the revenue from that sale may not qualify for recognition in the financial statements. Under Ind AS 115, Revenue from Contracts with Customers, a property sale does not automatically translate into accounting revenue. The developer must assess when control of the property transfers to the customer and whether the conditions for recognising revenue over time are satisfied. The distinction that matters Consider a developer who sells an apartment for ₹1 crore while construction is still underway. The buyer has signed the agreement and paid the initial instalment. Construction is progressing, and the sales team has recorded the transaction as a booking. From a business perspective, the sale is an important milestone. But the accounting assessment requires a different examination. Has the developer satisfied its performance obligation, or is it still required to deliver the property to the customer? That distinction determines whether revenue can be recognised as construction progresses or only when control transfers at a particular point in time. When can a developer recognise revenue over time? Ind AS 115 permits revenue recognition over time when at least one of the criteria in paragraph 35 is met. For real estate developers, paragraph 35(c) is particularly relevant. It requires both of the following: The second condition deserves particular attention. A builder may have entered into a binding agreement and collected an advance. However, if the buyer terminates the contract, can the developer legally enforce a right to payment that compensates it for the work completed to date? The answer depends on the contract terms, applicable law and relevant legal precedents. Cancellation clauses, termination rights and the legal framework, including applicable RERA provisions, may all be relevant to the assessment. A payment schedule linked to construction milestones does not, by itself, establish an enforceable right to payment for performance completed to date. The developer must evaluate the substance of its contractual and legal rights rather than assume that revenue can be recognised progressively. The Institute of Chartered Accountants of India has also clarified that Ind AS 115 permits revenue recognition as construction progresses when the prescribed criteria are satisfied. The assessment must be made with reference to the facts and circumstances of the individual contract. What if the criteria are not met? Revenue is recognised at a point in time when control of the property transfers to the customer. The developer must assess the relevant indicators of control, including the customer’s rights to the property, possession, legal title, payment entitlement and acceptance, where applicable. Possession or registration may provide important evidence, but neither should be treated as an automatic answer without examining the contractual arrangements and the facts. This is where the timing of revenue recognition can materially affect reported performance. Suppose the developer has sold several apartments during a financial year, but the applicable recognition criteria are satisfied only when control transfers later. The bookings may be strong. Customer advances may have been received. Construction expenditure may have accumulated. Yet, the revenue and associated profit may not appear in the same period in which the sales team reports those bookings. The difference is not merely a matter of presentation. It can affect quarterly revenue, reported margins, profit trends, contract balances and the interpretation of financial performance by lenders and investors. What should finance teams examine? For a real estate developer, the revenue recognition assessment should not be left until financial statement finalisation. Finance teams should examine: These assessments should be documented and applied consistently to contracts with similar characteristics, while accounting for differences that may affect the conclusion. The commercial takeaway Property bookings tell management how much business has been contracted. Cash collections show how much money has come in. Construction progress indicates how far the project has advanced. Recognised revenue answers a different question: how much of the developer’s contractual performance qualifies for recognition under the applicable accounting standard? For real estate businesses, keeping these measures distinct is essential to understanding financial performance and avoiding premature revenue recognition. The sale may be commercially significant from the day the agreement is signed. The accounting recognition, however, must follow the requirements of Ind AS 115.
When Falling Steel Prices Become an Accounting Problem
Why inventory can suddenly be worth less even though nothing physically changed Imagine a steel manufacturer closing its books at year-end. The warehouse looks exactly the same as it did three months ago. Same steel coils. Same quantity. Same quality. Same storage location. But there is one big difference. Steel prices have fallen. And suddenly, the finance team has an accounting question: Is the inventory still worth what we paid for it? This is where a change in the market can become an accounting issue. The Physical Inventory Hasn’t Changed. Its Economic Value Has. This is one of the interesting things about inventory accounting. We often think of an asset losing value when something happens to it physically. A machine breaks. A building deteriorates. A product gets damaged. But inventory can lose value even when nothing happens to the inventory itself. If market conditions change and the amount the company expects to recover from selling that inventory falls below its carrying amount, the financial statements may need to reflect that decline. For a steel company, a significant fall in steel prices can therefore have a direct impact on reported profitability. Here’s a Simple Example Suppose a company purchases steel inventory for ₹100 crore. At the reporting date, steel prices have fallen significantly. The company now estimates that it can recover only ₹90 crore from the inventory after considering the relevant selling and completion costs. The warehouse hasn’t changed. The accounting question has. The company may need to recognize a ₹10 crore write-down so that the inventory isn’t carried above the amount expected to be recovered from it. And that ₹10 crore doesn’t simply disappear from an Excel sheet. It can affect the company’s profit, margins, asset values and management’s view of performance. This Is Where Management Judgment Matters The difficult question isn’t: “Did steel prices fall?” That’s easy to observe. The harder question is: “What can we realistically recover from this inventory?” Finance teams may need to consider: This is where accounting moves beyond simply recording transactions. It requires judgment about economic reality. And Here’s the Interesting Part A company could have: More inventory than last year. The same physical inventory quality. The same warehouse. And still report: Lower inventory value. Because financial statements aren’t designed to tell us only what something costs. They also need to reflect what that asset is expected to be worth or recoverable for reporting purposes under the applicable accounting requirements. Why CFOs Should Care For commodity-driven businesses, falling prices can quickly move from the trading floor to the financial statements. A decline in inventory values can affect: And if management identifies the issue only during the year-end audit, the conversation can become much more difficult. The Bigger Lesson This is why accounting isn’t just about looking backward. Good financial reporting also asks what today’s market conditions mean for yesterday’s purchases. The steel sitting in the warehouse may look exactly the same. But its economic story may have changed. And sometimes, the most important accounting adjustment isn’t caused by something happening to the asset. It’s caused by what is happening around it. When prices move sharply, don’t wait until year-end to ask: “Is our inventory still worth what we think it is?” That conversation should start much earlier. Have falling commodity prices ever forced your organization to revisit its inventory valuation?
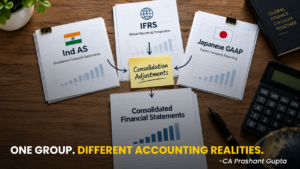
When One Group Has Two Accounting Realities
Why the same transaction can look different under Japanese GAAP, Ind AS and IFRS and why consolidation exists to bring the stories together Imagine a Japanese company with a growing Indian subsidiary. The Indian finance team closes its books under Ind AS. The parent company reports under Japanese GAAP. Now the group is preparing its consolidated financial statements. A transaction has already been recorded. The numbers are correct. The accounting teams have followed their respective standards. And yet, when the parent looks at the transaction, the accounting outcome may not look exactly the same. So who is right? Potentially, both. That is the interesting part of group accounting. One Transaction. Different Accounting Lenses. Accounting standards are not simply different languages for recording numbers. They can have different recognition, measurement, presentation and disclosure requirements. So the same underlying business event can produce different accounting outcomes depending on the reporting framework being applied. For a multinational group, this creates an interesting situation: The subsidiary has one accounting reality. The parent has another reporting reality. And that’s where consolidation becomes important. Think of It Like Translation Imagine a Japanese parent and its Indian subsidiary having a conversation. The subsidiary speaks Ind AS. The parent speaks Japanese GAAP. Neither is necessarily “wrong.” But if the group wants to present one set of consolidated financial statements, the numbers have to be brought onto a common reporting basis. That’s where group reporting and consolidation adjustments come in. The subsidiary’s financial statements become an important starting point but they aren’t necessarily the final answer for the group. Where Does IFRS Fit In? The situation becomes even more interesting when the group has operations or reporting requirements involving IFRS. Now finance teams may need to understand three different frameworks: Japanese GAAP → Ind AS → IFRS And the challenge isn’t simply knowing the standards individually. The real challenge is understanding: Where do they differ, and what does that difference mean for the group’s financial statements? Why This Matters to Finance Teams This becomes particularly important when multinational groups have: A local finance team may believe: “Our financial statements are compliant.” And they may absolutely be correct. But the group reporting team may still come back with: “We need an adjustment for group reporting.” That isn’t necessarily a contradiction. It is the consequence of preparing financial information for different reporting purposes and frameworks. Consolidation Is More Than Adding Numbers One of the easiest misconceptions about consolidation is: Subsidiary + Parent = Consolidated Financial Statements. It isn’t that simple. Consolidation is about bringing the financial information of different entities together while ensuring that the group is presented as one economic entity for reporting purposes. That may require adjustments to align accounting policies and reporting requirements before the numbers tell one coherent group story. The Real Challenge Isn’t the Standards I’ve found that the difficult part for finance teams is often not understanding an individual accounting standard. It is understanding the interaction between standards. A finance professional working for an Indian subsidiary may be extremely comfortable with Ind AS. But when the parent asks for numbers under Japanese GAAP or IFRS, a different set of questions appears: These questions sit at the intersection of technical accounting and practical group reporting. The Bigger Lesson As businesses become increasingly global, finance professionals are no longer working within a single accounting framework. A Japanese company with Indian operations, for example, may have to navigate multiple accounting perspectives before presenting one consolidated financial story. And that’s why understanding accounting standards individually isn’t enough. You also need to understand how they connect. Because at the end of the day, consolidation isn’t about deciding which accounting reality is “right.” It is about bringing different reporting realities together to tell one reliable story about the group. Have you ever prepared an Ind AS financial statement only to receive a group reporting adjustment from the parent company? What was the biggest difference you encountered?
Managing “Day 2” Complexities in Heavy Machinery & Fleet Leases
Why Excel Models Break Down After IFRS 16 Goes Live When IFRS 16 first came into effect, most companies focused on one thing: Getting implementation done. Lease inventories were prepared. Discount rates were determined. Right-of-use assets were recognised. Lease liabilities were calculated. Project complete. Or so everyone thought. But the real challenge didn’t begin on Day 1. It began on Day 2. Compliance Was Never the End Goal Imagine a logistics company with a fleet of 600 leased trucks. Six months later: Or consider a cement manufacturer. Its quarry equipment lease is modified after production forecasts change. The company expands one plant, closes another, and renegotiates warehouse leases across multiple states. None of these are unusual business events. They’re simply how businesses operate. The challenge is that every one of these decisions has accounting consequences. IFRS 16 Didn’t Just Change Lease Accounting It changed how companies manage leases. Under older accounting models, many lease modifications simply affected future rental expenses. Today, a modification can trigger: What looks like a commercial negotiation in the procurement department can become a significant accounting event for the finance team. Why “Day 2” Is So Difficult The initial implementation of IFRS 16 was largely a one-time exercise. Day 2 is continuous. Leases evolve. Businesses grow. Assets are replaced. Facilities are expanded. Contracts are renegotiated. Finance teams must continuously evaluate whether those changes represent: The accounting depends on understanding the commercial substance, not just updating a spreadsheet. Why Excel Eventually Reaches Its Limits Many organisations initially managed lease accounting through sophisticated Excel models. For a handful of leases, that works. But imagine tracking: The issue isn’t that Excel calculates incorrectly. The issue is that businesses change faster than spreadsheets are designed to manage. Version control becomes difficult. Audit trails weaken. Manual interventions increase. The risk shifts from accounting complexity to operational complexity. The Bigger Lesson One of the biggest misconceptions about IFRS 16 is that it’s merely an accounting standard. It isn’t. It’s also a data governance challenge. Successful compliance today depends as much on communication as on technical accounting. Procurement teams. Operations. Legal. Treasury. Finance. All need to know when a lease change occurs, because accounting is often the last function to hear about it, yet the first expected to report it accurately. Looking Beyond Compliance Companies that manage Day 2 effectively don’t just have better accounting policies. They have better processes. Lease modifications are identified early. Responsibilities are clearly assigned. Systems capture changes as they happen, not months later during the audit. In other words, they treat lease accounting as a living process rather than a completed implementation project. Final Thought The biggest misconception about IFRS 16 was that implementation marked the finish line. In reality, implementation was only the starting point. The real test isn’t whether your lease model worked on Day 1. It’s whether it still reflects economic reality after two years of contract renegotiations, fleet expansions, facility closures, and changing business needs. Because leases don’t remain static. And neither should the accounting that reflects them.
Functional Currency Dilemmas in Cross – Border Joint Ventures
When your business operates in India, invoices in USD, borrows in JPY, and reports in INR – which currency tells the real story? Imagine this. An Indian company enters into a joint venture with a Japanese partner. The manufacturing facility is in Gujarat. Employees are paid in Indian Rupees. Taxes are paid in India. But most customers are overseas. Sales contracts are denominated in USD. Raw materials are imported from Japan and settled in JPY. At the end of the year, the finance team notices something strange. Revenue has grown. Operations have remained stable. Cash flows are healthy. Yet reported profits have become unusually volatile. What changed? Often, the answer isn’t the business. It’s the functional currency. The Currency That Matters Most Isn’t Always the One You Report In Many people assume that a company’s accounting is prepared in the currency of the country where it operates. That’s not necessarily true. Under IAS 21 The Effects of Changes in Foreign Exchange Rates and Ind AS 21 The Effects of Changes in Foreign Exchange Rates, every entity must first identify its functional currency – the currency of the primary economic environment in which it operates. Notice the emphasis. Not where the company is incorporated. Not where the head office is located. But where its business is fundamentally driven. Because accounting isn’t interested in geography. It’s interested in economic reality. Why Functional Currency Is More Than an Accounting Choice Choosing a functional currency is not an administrative exercise. It determines how almost every foreign currency transaction is accounted for. More importantly, it determines where exchange differences appear in the financial statements. If the functional currency truly reflects the business model, exchange movements largely represent genuine economic exposure. But if the functional currency is chosen incorrectly, the financial statements can begin telling a misleading story. A business that is operationally stable may suddenly appear highly volatile. Margins fluctuate. Foreign exchange gains and losses swing dramatically. Performance comparisons become difficult. Nothing changed in the business. Only the accounting lens changed. A Practical Example Consider an Indian automotive component manufacturer. Its factory, workforce, and operations are entirely based in India. However, almost 90% of its sales are exported to the United States under long-term USD contracts. Management decides to retain INR as its functional currency because the business is located in India. Over the next year, the rupee weakens sharply. Every reporting period, large foreign exchange gains and losses begin flowing through the profit and loss account. Investors may conclude that earnings have become unpredictable. In reality, the underlying business hasn’t changed significantly. The apparent volatility may simply be the result of measuring the business through a currency that doesn’t best reflect its primary economic environment. The numbers are technically correct. But do they faithfully represent business performance? That’s the question IAS 21 is designed to answer. Looking Beyond the Invoice One common misconception is that the invoicing currency determines functional currency. It doesn’t. IAS 21 asks management to consider several factors together: No single indicator decides the answer. Professional judgement does. And that judgement becomes increasingly important for multinational groups, export-oriented manufacturers, technology companies, and cross-border joint ventures. Why This Matters More Than Ever Today’s businesses rarely operate within one economic ecosystem. An Indian company may: Business has become global. Financial reporting must determine which currency best represents that economic reality. The answer is rarely obvious. The Bigger Lesson IAS 21 isn’t really about foreign exchange. It’s about faithful representation. The objective isn’t to eliminate currency fluctuations. It’s to ensure that financial statements distinguish between: Those are not the same thing. When functional currency is determined thoughtfully, exchange differences tell investors something meaningful. When it’s determined poorly, they can become little more than accounting noise. Final Thought Currencies do more than settle transactions. They shape how performance is measured, risks are perceived, and businesses are valued. That’s why determining functional currency is not just an accounting decision. It’s a strategic judgement about what truly drives the business. Because sometimes, the biggest risk isn’t foreign exchange. It’s measuring a global business through the wrong currency.
Can Accounting Measure Innovation?
Imagine two companies. The first buys a manufacturing plant for ₹500 crore. The second spends ₹500 crore developing an AI platform, hiring world-class engineers, building proprietary datasets, and filing patents for a breakthrough technology. A few years later, which company is likely to be more valuable? Increasingly, the answer is the second. Yet accounting tells a different story. The manufacturing plant appears as an asset on the balance sheet. Much of the investment in innovation is recognised as an expense. At first glance, it feels unfair. Is accounting failing to recognise what truly creates value? Or is it solving a much more difficult problem? Innovation Is an Investment… But Not Every Investment Becomes an Asset Businesses today invest heavily in things that cannot be touched. Research. Software. Algorithms. Drug pipelines. Brands. Customer relationships. Human capital. These are often the very reasons investors value a company. So why doesn’t accounting recognise all of them as assets? Because accounting isn’t trying to answer one question. I’m trying to answer two. Has value been created? And equally important, Can that value be measured reliably? The first question is often easy. The second is where the challenge begins. The Problem Isn’t Innovation. It’s Uncertainty. Imagine a pharmaceutical company developing a new drug. Years of research. Thousands of scientists. Hundreds of crores invested. Yet the drug may never receive regulatory approval. Or consider an AI startup building a large language model. Will customers adopt it? Will a competitor build something better six months later? No one knows. Innovation creates possibilities. Accounting requires evidence. That difference explains why accounting standards remain cautious. Why Accounting Prefers Verifiable Value Suppose companies were allowed to recognise the estimated value of every internally developed idea, brand, or technology. Financial statements would become far more exciting. They would also become far less reliable. Every balance sheet would depend heavily on management’s optimism. Two companies working on similar innovations might report completely different asset values simply because their assumptions differ. Investors would struggle to compare them. Accounting avoids this problem by setting a high threshold for recognition. Not because innovation lacks value. But because uncertainty is difficult to measure objectively. The Growing Gap Between Book Value and Business Value This explains one of the biggest paradoxes in modern business. The world’s most innovative companies often report balance sheets that appear surprisingly modest. Their factories matter. But their competitive advantage lies elsewhere. In ideas. Knowledge. Data. Intellectual property. Customer trust. The market recognises this value. Accounting recognises it only when it can be supported with sufficient evidence. As economies become more knowledge-driven, this gap is becoming wider, not smaller. So, Is Accounting Broken? Perhaps we’re asking accounting to do something it was never designed to do. Financial statements are not meant to estimate a company’s future potential. They are meant to report economic resources with reasonable confidence. Innovation, by its very nature, is uncertain. It involves experimentation, failure, iteration, and possibility. Those qualities make businesses valuable. They also make accounting cautious. Final Thought Can accounting measure innovation? To some extent, yes. But it can never measure potential with the same confidence that it measures proof. And maybe that’s exactly how it should be. Innovation fuels the future. Accounting documents what can be trusted today. The real challenge for investors isn’t choosing between the two. It’s understanding that the most valuable part of a business may be the part financial statements are intentionally reluctant to measure.